Market overview — definition, scope, and industry significance of Revision Knee Replacement Market
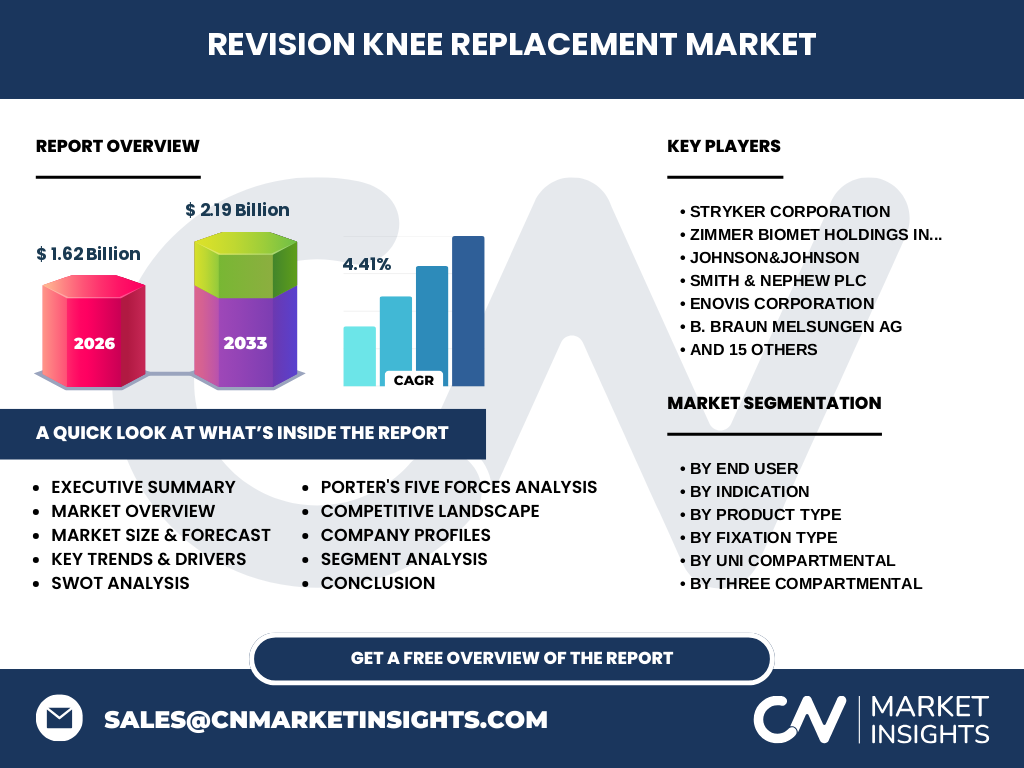
Our analysis indicates that the Revision Knee Replacement Market market size stands at $1.62 Billion in 2026. This specialized surgical sector addresses failed primary arthroplasties requiring component exchange. The scope encompasses complex hardware removal, bone loss management, and specialized articulating surfaces requiring advanced metallurgy like cobalt-chromium-molybdenum alloys and titanium sleeves.
Key market drivers, restraints, challenges, and opportunities shaping Revision Knee Replacement Market
The primary growth catalyst is the rising global volume of primary arthroplasties facing eventual wear-induced aseptic loosening. Conversely, stringent FDA PMA approvals and CE-MDR compliance protocols act as market restraints. Procedural complexity and the necessity for specialized surgical training present ongoing clinical challenges, while emerging custom 3D-printed porous titanium cones offer significant commercial opportunities.
Structural Growth Drivers
Demographic shifts toward an aging global population heavily propel the Revision Knee Replacement Market industry trends. Higher life expectancies directly correlate with increased cumulative joint wear. Furthermore, rising revision rates among younger, more active patient cohorts demand durable implant systems capable of withstanding higher biomechanical loads over extended postoperative lifespans.
COVID-19 impact analysis — how the pandemic affected Revision Knee Replacement Market and the recovery trajectory
Pandemic-era elective surgery halts severely depressed procedural volumes. However, our research highlights a robust rebound driven by surgical backlog prioritization. Supply chain bottlenecks involving medical-grade titanium and sterile packaging have largely resolved, allowing manufacturers like Zimmer Biomet Holdings Inc. and Stryker Corporation to stabilize global distribution.
Competitive Benchmarking
The competitive landscape is dominated by multinational medtech titans maintaining high market concentration. Stryker Corporation and Johnson&Johnson leverage extensive orthopedic portfolios and proprietary robotic navigation ecosystems, whereas regional innovators like AK Medical Holdings Limited and Beijing Chunlizhengda Medical Instruments Co. Ltd. capture share through cost-optimized, domestically approved joint reconstruction systems.
Executive summary — high-level synthesis of key findings about Revision Knee Replacement Market
Our research projects the market to expand from $1.62 Billion in 2026 to $2.19 Billion by 2033 at a steady 4.41% CAGR. Aseptic loosening and infection remain the principal clinical indications driving high-value product utilization, particularly in advanced hospital and specialized orthopedic clinic settings.
Market forecast — projected growth from 2027 to 2033
The data suggests sustained expansion across the forecast horizon, scaling the market valuation from its 2026 baseline to $2.19 Billion by 2033. This trajectory represents a stable 4.41% CAGR, underpinned by improving healthcare infrastructure in emerging economies and rising revision surgical rates worldwide.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation is categorized by end user, indication, product type, and fixation type. End users include Hospitals, Orthopedic Clinics, and Ambulatory Surgical Centers. Indications cover Aseptic Loosening and Infection. Product types span Three Compartmental and Uni Compartmental systems, while fixation includes Cemented, Cementless, and Hybrid Fixation Systems.
Regional market analysis — geographic distribution and performance across regions
North America commands the largest revenue share due to high primary knee arthroplasty volumes and advanced ambulatory surgical infrastructure. Meanwhile, Asia-Pacific represents the fastest-growing regional market, fueled by expanding healthcare expenditure, rising disposable incomes, and an expanding elderly demographic base in nations like China and Japan.
In-depth regional review — detailed examination of key regional markets
In North America, stringent hospital reimbursement policies encourage efficient utilization of advanced revision hardware. Europe demonstrates steady adoption constrained by rigorous regulatory hurdles under the European Medical Device Regulation. Meanwhile, Asia-Pacific showcases rapid modernization of orthopedic operating theaters, attracting major investments from international firms and domestic manufacturers alike.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct competitive strategies to defend and expand their footprint. Smith & Nephew plc and Medacta International SA focus on patient-specific instrumentation and kinematic alignment technologies. Meanwhile, Enovis Corporation and Corin Group emphasize modular revision portfolios designed to simplify complex intraoperative bone defect reconstructions.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to strict purity requirements for medical-grade raw materials. Buyer power is counterbalanced by the high clinical switching costs associated with specialized orthopedic instrumentation. Threat of substitutes is remarkably low given the irreversible nature of advanced joint failure requiring structural hardware replacement.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths include proprietary implant metallurgy and robust surgeon training programs. Weaknesses involve high capital expenditure requirements for specialized inventory. Opportunities lie in expanding into underserved emerging markets. Threats encompass stringent regulatory compliance costs and potential pricing pressures from hospital group purchasing organizations.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain initiates with the sourcing of biocompatible raw metals, followed by precision CNC machining and porous coating application. Component sterilization and packaging occur prior to distribution via specialized logistics hubs to major hospital systems and orthopedic clinics where skilled surgeons perform the complex arthroplasty procedures.
Investment insights — strategic recommendations and high-potential areas
Investors should target developers of modular revision systems and antimicrobial implant coatings designed to combat periprosthetic joint infections. Companies integrating AI-driven preoperative planning software with hardware solutions exhibit the strongest potential for capturing high-margin market share through enhanced surgical precision.
Conclusion and key takeaways
The Revision Knee Replacement Market analysis confirms steady, resilient expansion toward $2.19 Billion by 2033 at a 4.41% CAGR. Stakeholders must prioritize technological innovation in modular fixation and infection management to successfully navigate regulatory scrutiny and capture expanding demographic-driven demand.
Research methodology — detail how baseline estimates are triangulated
Our analytical framework triangulates baseline estimates by synthesizing secondary macroeconomic indicators, national joint registry databases, and primary stakeholder interviews with orthopedic surgeons and procurement directors. This rigorous cross-verification guarantees high-fidelity market sizing and growth forecasting across all identified segments.
Scope of the report — coverage parameters and limitations
This report covers global revenue performance, volume projections, and strategic landscape dynamics from 2026 to 2033. Limitations include inherent macroeconomic uncertainties, unforeseen regulatory shifts in key international markets, and localized healthcare reimbursement policy alterations that may impact procedural adoption rates.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent industry momentum features expanded regulatory clearances for advanced modular knee revision platforms by key players such as Waldemar Link GmbH & Co. KG and United Orthopedic Corporation. Strategic acquisitions and distribution partnerships continue to reshape the competitive hierarchy as companies race to bolster their global commercial footprint.